850-753-0041


Homeowners Insurance Cancelled Because of Roof? Next Steps
November 2, 2026
8 minutes Read
Opening a letter that says your coverage is ending can feel like the ground just shifted under your home. If you’re dealing with homeowners insurance cancelled because of roof age or condition, you’re far from alone, especially along the Gulf Coast where homeowners insurance companies have tightened their rules after years of storm losses. The good news is that you have options, and many homeowners in Pensacola restore their coverage faster than they expect. Often the fix starts with a professional inspection and, when needed, a roof replacement built for Florida weather.
In this guide, you’ll learn:
- Why it happens: The most common roof issues that lead insurers to cancel or nonrenew a policy.
- Your rights: What Florida law says about roof age and insurance eligibility.
- Next steps: A clear action plan to follow the moment you receive the notice.
- Your options: How inspections, repairs, and replacements compare.
- Insurability upgrades: Roof improvements that can help you qualify for coverage and discounts.
Why Insurance Companies Drop Policies Over a Roof

Your roof is the first line of defense against wind and rain, so insurers see it as one of the biggest predictors of future insurance claims. When an underwriter spots an older roof or signs of wear, they may decide the risk of a costly claim is too high and choose to cancel or not renew the homeowners insurance policy.
Florida does give homeowners some protection. Under state law, an insurer may not refuse to issue or renew a homeowners policy solely because the roof is less than 15 years old. If your roof is 15 years or older, the insurer must let you get an inspection from an authorized inspector, and if it shows at least five years of useful life remaining, roof age alone can’t be the reason for refusal.
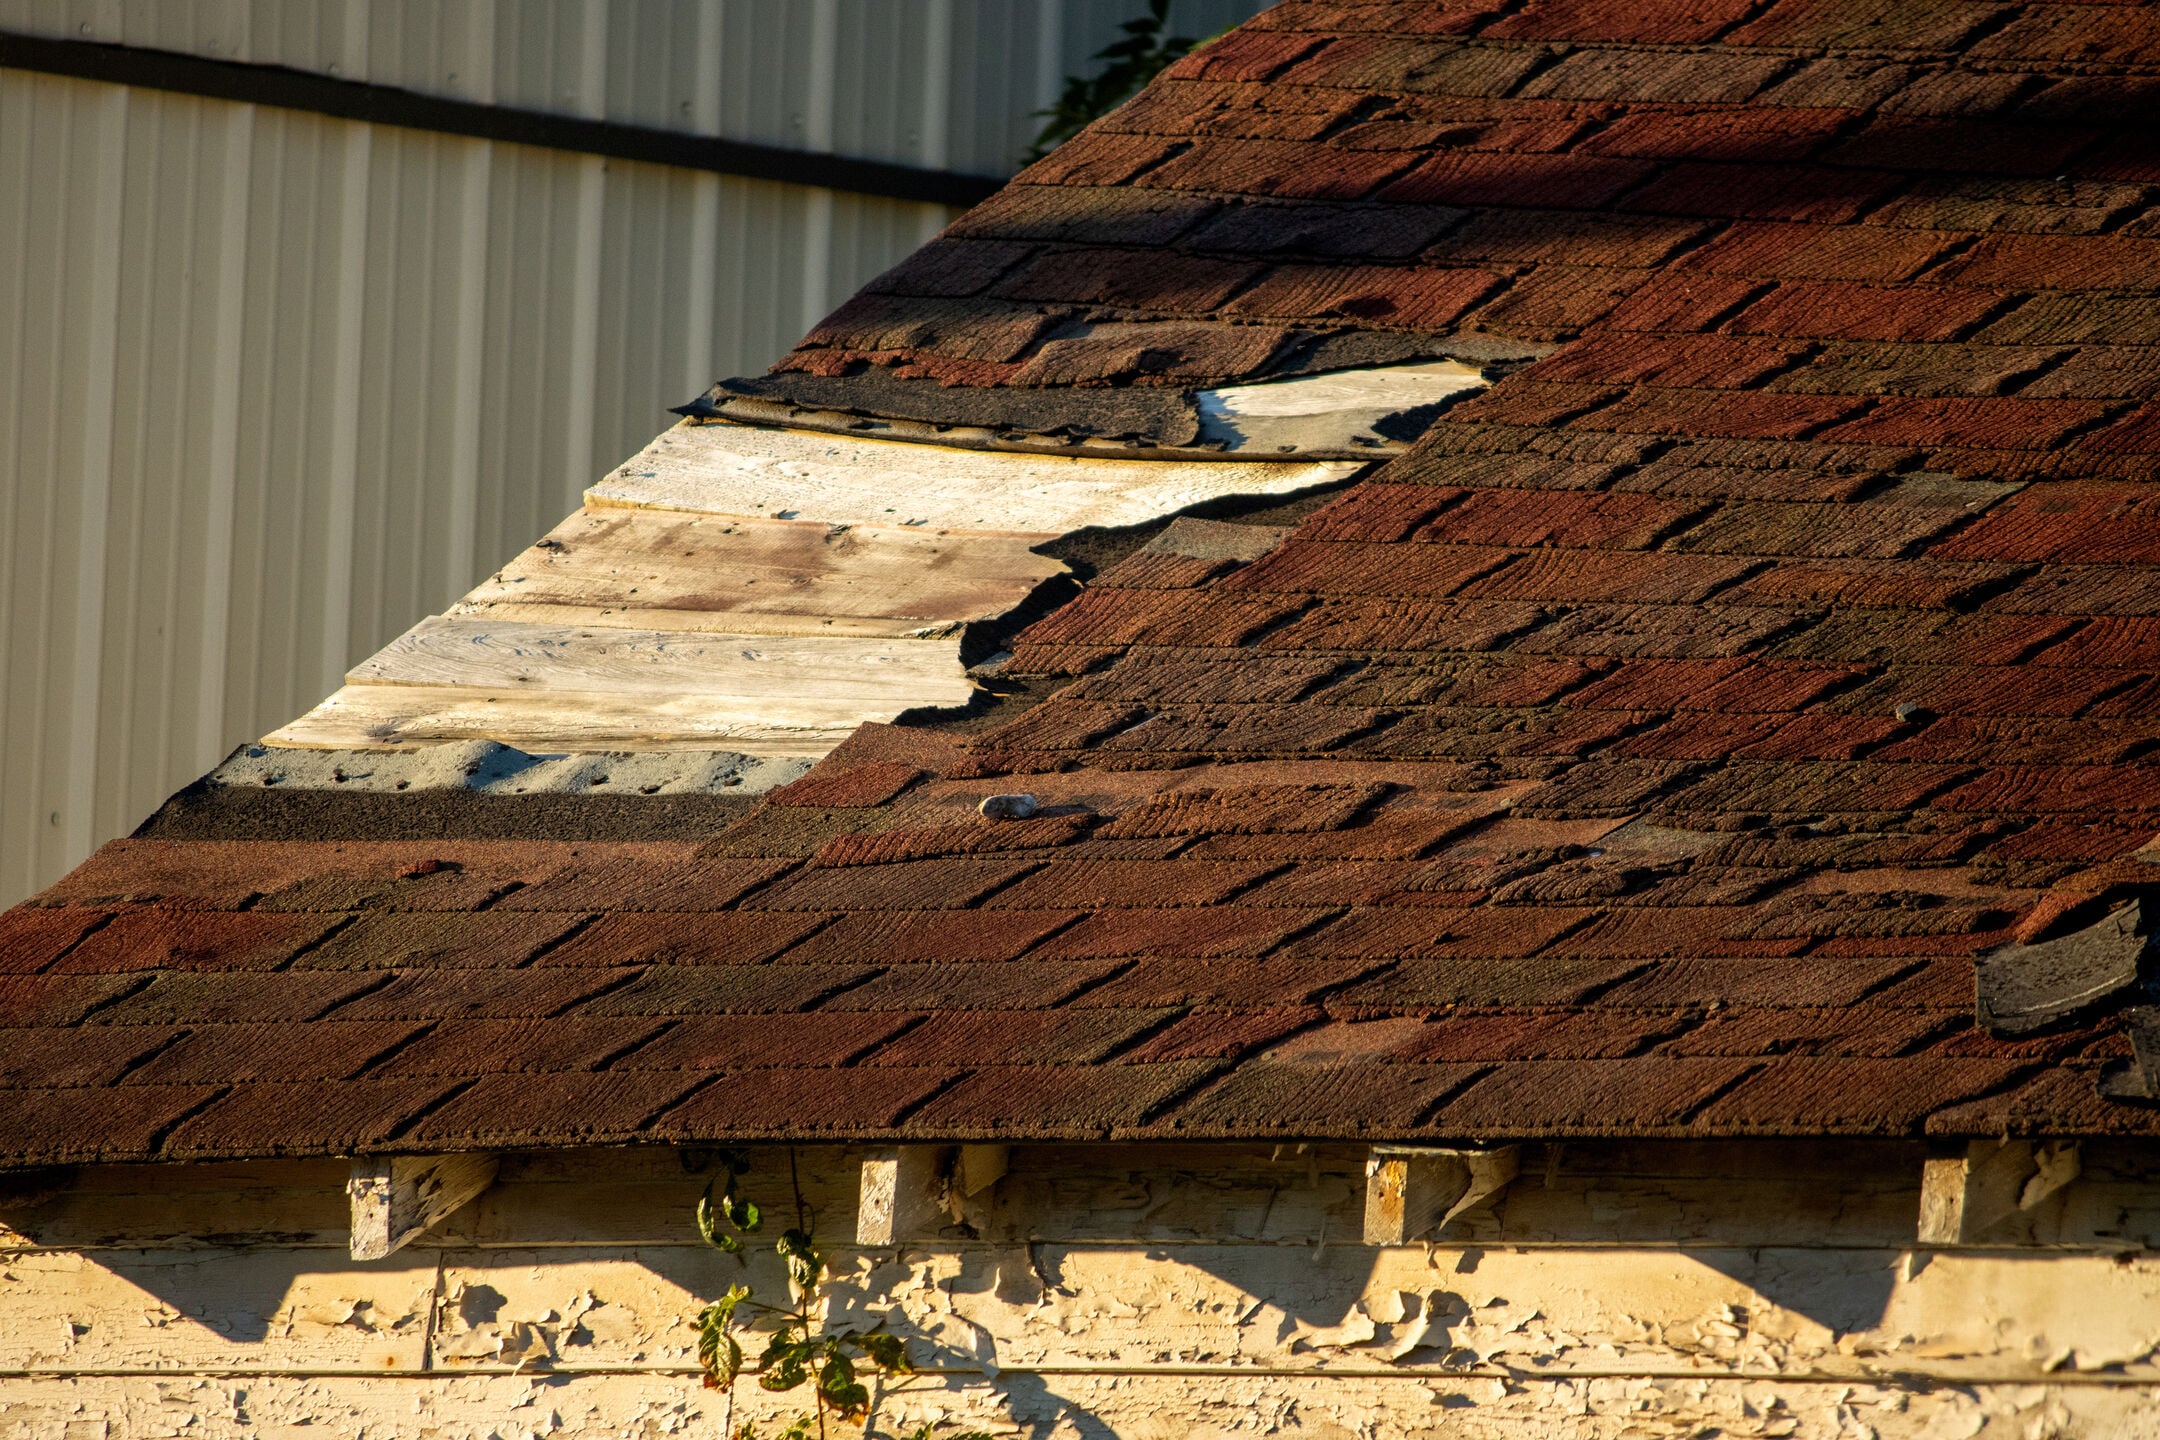
That said, insurers can still act on the actual condition of your roof. Common triggers include:
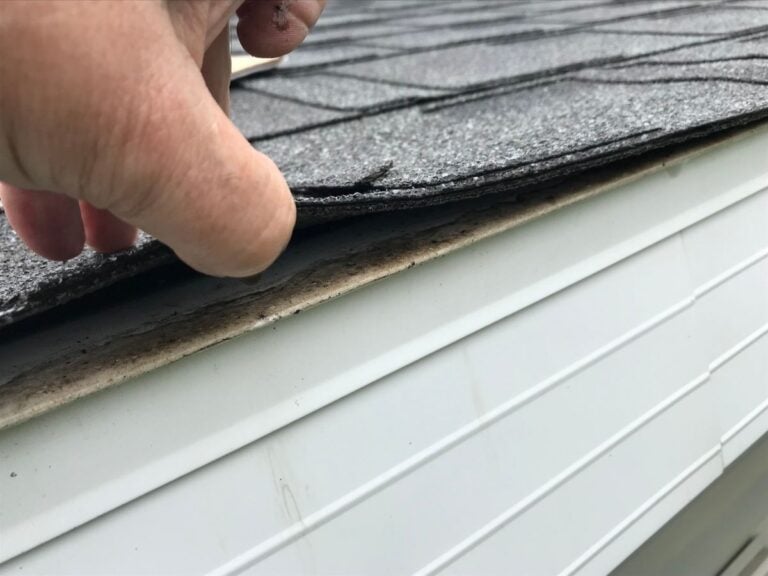
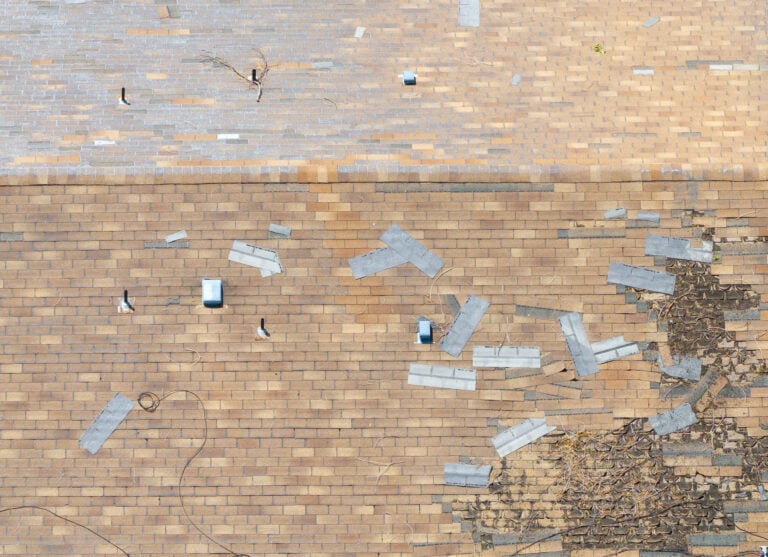
- Visible damage: Missing, curled, or cracked shingles spotted during an exterior or aerial inspection.
- Active leaks: Water stains, soft decking, or evidence of past leaks that were never repaired.
- Age without documentation: Roofs over 15 years old with no inspection showing remaining useful life.
- Outdated materials: Roof types the carrier considers high risk, such as older three tab shingles.
- Unrepaired storm damage: Roof damage from a previous hurricane or windstorm that was never addressed.
7 Steps to Take After Your Policy Is Cancelled
Acting quickly matters, because a lapse in coverage can put your mortgage at risk and leave your home exposed during storm season. Follow these steps in order to protect both your home and your wallet.
- Read the notice carefully: Look for the exact reason, the effective date, and whether it’s a cancellation or a nonrenewal, since each follows different rules and timelines.
- Call your insurance agent right away: Ask which specific roof findings triggered the decision and whether new documentation could reverse it.
- Schedule a professional roof inspection: A licensed roofing contractor can document your roof’s true condition, age, and remaining useful life with photos.
- Make required repairs or plan a replacement: If the inspection confirms damage, schedule roof repairs promptly and keep every invoice, permit, and warranty.
- Notify your mortgage lender: Let your lender know you’re securing new coverage so they don’t buy a more expensive policy on your behalf.
- Shop for new coverage: Compare quotes from more than one insurance provider through an independent agent, and ask about Citizens Property Insurance if private options are limited.
- Request a wind mitigation inspection: Once your roof is in good shape, this report documents storm resistant features and may lower your premium.
Comparing Your Roof Options for Insurance

Not every cancellation requires a brand new roof. The right path depends on your roof’s age, its condition, and what your carrier needs to see before writing or renewing a policy.
| Option | Best For | Typical Timeline | Insurance Impact |
| Inspection and roof certification | Roofs 15+ years old that are still in good shape | A few days | Can show five or more years of useful life remaining |
| Targeted repairs | Isolated issues like missing shingles or failed flashing | One to several days | Resolves specific underwriting concerns |
| Full roof replacement | Aging roofs, widespread damage, or repeated leaks | One to three days for most homes, plus permitting | Resets roof age and may qualify for wind mitigation credits |
In Pensacola, where humidity, salt air, and hurricane season all speed up wear, an honest inspection is the best way to know which option truly makes sense for your home.
How to Make Your Roof More Insurable in Florida
Some upgrades do more than help you pass an inspection. They can make your home more attractive to insurers, help lower your premium over time, and make it easier to find a policy that will cover roof damage from future storms.
- Impact rated shingles or metal roofing: Materials designed for high winds and flying debris hold up better during Gulf Coast storms.
- Secondary water barrier: A sealed roof deck helps keep water out even if shingles are lost in a storm.
- Upgraded roof to wall connections: Hurricane clips or straps help keep the roof attached to your home in high winds.
- FORTIFIED construction: Building to the FORTIFIED Roof standard from the Insurance Institute for Business & Home Safety may qualify you for additional discounts.
- Organized documentation: Keeping permits, warranties, and inspection reports in one place makes renewals and carrier switches much easier.
We’re proud to serve home and business owners in Pensacola, FL, and nearby communities with roof inspections, storm resistant roof replacements, and more.
Common Questions About Roof Related Insurance Cancellations
Homeowners facing a cancellation tend to ask the same handful of questions. Here are straightforward answers to the ones we hear most often.
Can my insurance company cancel my policy just because my roof is old?

It depends on the age of the roof and its condition. In Florida, an insurer can’t refuse to issue or renew a policy solely because your roof is under 15 years old. Once a roof passes that mark, the carrier can require replacement unless an authorized inspection shows at least five years of useful life remaining. Keep in mind that insurers can still act on actual damage or poor condition at any age, so regular maintenance matters just as much as the date on your permit.
How long do I have to find new coverage?
Your notice will list an effective date, and Florida law requires insurers to give advance written notice before a cancellation or nonrenewal takes effect. The exact amount of notice depends on the type of action and how long your policy has been in force, so read the letter closely. Start shopping right away rather than waiting, since any gap in insurance coverage leaves your home unprotected, and new carriers may want an inspection report or proof of repairs before they write a policy, and scheduling that work takes time.
Will a new roof lower my insurance premium?
In many cases, yes. A new roof resets the roof age that insurers use for rating, and modern materials installed to current Florida Building Code standards often qualify for wind mitigation credits. After installation, request a wind mitigation inspection and send the report to your agent so those discounts appear on your policy. Savings vary by carrier and home, but a newer roof also widens the pool of home insurance carriers willing to offer you coverage in the first place.
Who can perform a roof inspection for insurance purposes?
Insurers generally accept inspections from licensed professionals such as roofing contractors, home inspectors, building code inspectors, and certain engineers, though each carrier may set its own approval rules. Before booking, ask your agent which inspectors and report formats your carrier accepts. Choosing an experienced local roofing contractor offers an added benefit, because the same team that documents your roof’s condition can explain your repair or replacement options and handle the work if it’s needed.
Get Your Coverage Back on Track With Quality Roofing Solutions
A cancellation notice doesn’t have to turn into a crisis. For 20 years, Quality Roofing Solutions has helped Gulf Coast homeowners understand exactly where their roofs stand and what it takes to keep them insurable. As a CertainTeed SELECT ShingleMaster with more than 10,000 satisfied customers, our team gives you honest recommendations without the pressure.
Whether your roof needs documentation, a repair, or a full replacement, we’ll walk you through every step and provide the paperwork your insurer wants to see. We offer free roof inspections, so there’s no cost to find out where you stand. Contact our team today to schedule yours and get your coverage back on solid ground.